

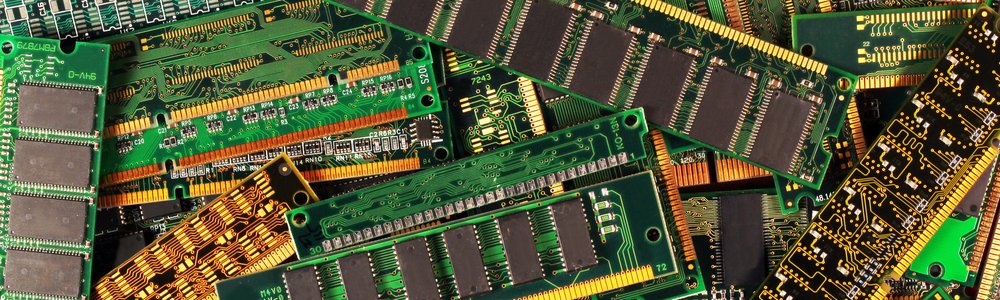
A global player in electronics distribution warned memory vendors have less than a week of inventory on hand, with supply chains not on track to restore until 2028.
Mike Pursley, chief trading officer at Smith, told SDxCentral that in his 35 years at the distributor, the ongoing memory shortage is the most severe to be faced by the electronics industry, both in volume and in absolute dollar terms.
“Parts that were $400 in May of 2025 in the open market are going for $3000 to $3,500 right now,” Pursley said. “Parts that were $175 to an enterprise customer direct are probably now going for $1600, so it's 10-fold, and that's direct from the manufacturer.”
Pursley framed the independent open market as fundamentally different to traditional procurement. Companies like Smith exist “to support the customers that are having supply chain shortages, where they're not being able to get full commitment from the channel,” such as when a customer places an order for 100,000 modules and can only get a commitment for 50,000.
“What do they do then? Do they wait another year to get that balance, or do they want to lead and build out immediately?” Pursley said, adding that only customers who can afford to pay [a] premium find themselves turning to the open market. This is when the need proves imminent, especially with money potentially going down the compute drain.
“Say you don't have parts, but you have the GPU, and you have the rack, you have the system, but you don't have the 64-gig modules or the 32-gig modules to fill it all out, you've got dead money sitting in machines without the memory. And so the biggest question is how do companies finance this? It is massive money. It's massive money not only for them; it's massive money to the distributors. You have to be well capitalized, well financed.”
Competing bids also jack up prices, making it “very difficult for anybody to get a sustainable supply because the product can go up in price so quickly.” Unsurprisingly, this has an impact on smaller clients, who have to wait patiently in line at the manufacturer level for supplies.
“They will get some product, but only 30 or 40% of what they're placing the order for, and so that's when you see customers get a little more desperate, and they may need 10,000, so they place an order for 20,000. But then, at some point in 2028, when supply might start balancing out, when they place those orders for the 20,000, 20,000 all of a sudden is going to get allocated to them, and if they don't have the budget to buy it all and take it all, then they need someone to take it off their hands, and they may come to a company like us to help partner with them and take on some of the overage that they have.”
While Pursley’s 2028 prediction considers the possibility of a stock price drop and manufacturing ramp-ups, the exec doesn’t see memory vendors changing anytime soon from committing to their most profitable lines of business, namely high-bandwidth memory.
Big vendors in that game like SK Hynix and Samsung have only over a week's inventory on hand, according to recent analysis from South Korean financial giant KB Securities.
Pursley thinks even this figure is over-optimistic.
“I don't think they have much of anything. So 10 days may be generous. They probably do hold very small quantities of certain things for customers that might need to spec in and do approvals or testing or qualifications for new builds on certain things, but there is no reason to hold inventory back right now.
"The margins are probably the highest these companies have ever worked on. They should be wanting to ship everything they can possibly ship as soon as it comes into inventory, because the customers are literally dying for the product. They can't get enough.”
No quick fixes
Elsewhere in the memory stronghold that is Asia, Pursley poured water on the idea of China becoming a serious source of memory chips.
“You hear about Apple wanting to use potentially Chinese versions of DRAM … but if the country of origin is China, that really restricts the customers that can use that product.”
Purlsey explained such components may incur significant tariffs if re-imported into the United States, limiting their viability except for clients with manufacturing and customer bases outside the U.S.
“If you find out the parts are made in Taiwan, you're generally in pretty good shape. But if you find out the customer’s in California, but the country of origin is China, the deal just doesn't work.”
In other words, there is no quick fix to the situation as things stand. Companies have the chance to go back to the drawing board to re-architect their systems, but Pursley says this only delays the inevitable.
“If you hesitate at the beginning of a shortage, and you wait a week. The price that they were discussing goes from $10, and you look up all of a sudden it's at $18, and they're like, ‘Well, how's that possible?’ They need to reevaluate … Some customers end up literally just not buying, and it could hold their production up three, four, five, six months until they get the product from the manufacturer or from authorized distribution. But there's no guarantee that the manufacturer won't increase the price 30, 40% when manufacturing is back up.”
Pursley also revealed Smith saw the warning signs as far back as May 2025, predating initial analyst red flags from the end of last year courtesy of the likes of Morgan Stanley.
With Pursley at the eye of the storm, as it were, SDxCentral asked what troubles to expect further down the line.
The response is a growing shortage in tantalum capacitors and multilayer ceramic capacitors (MLCC), which are both used to store charge, smooth voltage, filter noise, and stabilize power rails. They are not only essential to networking, compute, data center and telecom equipment, but “everything you touch”, Pursley said.
“A lot of the enterprise storage companies are in a global shortage for this stuff. Parts that normally are ¢0,0035, and customers need 20, 30 million at a time, are going for 10,15, 20 cents a piece. That is like 1,000% exponential demand.”


Comments