


In warehouses across the U.S. and Europe, cards sit patiently in climate-controlled storage, waiting for the day they'll finally be put to their intended use. Some are silicon. Some are cardboard. The economics keeping both within limbo are remarkably similar.
The links between semiconductors and Pokémon cards may not be immediately obvious. But if you've watched either market spiral into speculative madness over the past few years and months, the parallels are hard to ignore.
The hoarding problem
It’s not a production problem, but one of would-be “investors” hoping to emulate Logan Paul and capitalize on artificial scarcity, stoking the very demand they hope to exploit.
Pokémon cards are printed in mass supply, yet many consumers are unable to get them at their local stores. Paul and his YouTuber friends published a series of unboxing videos (that’s where they buy a Pokémon box to reveal its contents in the hopes of finding rare cards) during the height of COVID, resulting in Poké fever resurging to levels not seen since the turn of the century.
When the YouTuber and wannabe boxer dropped $5.2 million on a PSA 10 Pikachu Illustrator card (a Guinness World Record purchase), scalpers worldwide took it as a sign to descend on every subsequent set release like Snorlax on a buffet.

Likewise then, the AI supercycle (to borrow Nokia parlance) has resulted in Nvidia GPUs being snapped up left and right, by everyone from speculative investors to AI-hungry venture funds, only for the chips to be left in warehouses, waiting to be deployed into a data center with sufficient power, cooling, and fiber connectivity.
A card, silicon or otherwise, is often only as hot as its latest iteration. The technology is rapidly advancing to such an extent that chipmakers like Nvidia and AMD felt the need to shift their product launches to an annual cadence.
Will stockpiled chips even see use once the capacity is there? Or will operators want the shiny new chip to make sure they’re hitting as much capacity as possible?
Dame Dawn Childs, CEO of Pure Data Centers, recently described GPUs as being “short life assets” with a “useful life of maybe three years until it has to be relegated to lower intensity tasks, or it might have even been superseded by the latest technology for chips coming out.”
She then likened CPUs and GPUs to aging in “dog years rather than normal years.”
Supply constraints have only amplified the frenzy at a time when hardware was scarce.
As ChatGPT proliferated in late 2022, the chip market was still recovering from the pandemic-induced shortage – something the Pokémon card market also saw, resulting in huge shortages and reduced product availability across both consumer and enterprise markets.
As a result, several wannabe investors took it upon themselves to snap up what was Nvidia’s flagship product at the time: the H100.
But by today’s standards, those chips are practically out of date – with the Blackwell and soon-to-launch Blackwell Ultra dominating the landscape until ultimately being replaced by Vera Rubin. And so on, so on the wheel of product goes.
Even without major supply chain shortages, concerns are still abound that the current supply of chips won’t meet future demand. London Economics, for example, says there’s no way the current supply of chips will meet the projected growth of the data center market, with the U.S. alone eating 90% of the global chip supply under current projections
So when headlines have begun to emerge that the memory chip market is already seeing panic buying amid more demand than supply, the parallels are hard to ignore.
In the past week alone, Morgan Stanley downgraded HPE, HP, and Dell stocks on the basis due to memory cost inflation pressures – a concept being dubbed the “memory supercycle,” with DRAM and NAND flash memory prices spiking between 50% and 300% in the past six months alone.
HPE demoted as Samsung memory prices soar amid AI demand
DRAM becomes a hot commodity as inference needs increase
What’s driving the memory rush? AI (because of course it is).
OpenAI recently signed a mega contract with both Samsung and SK Hynix for a cumulative 900,000 DRAM wafer starts per month – that roughly translates to around 40% of global DRAM output.
While questions over OpenAI’s finances loom over it like the Gengar at the feast, that deal has already caused panic buying and hoarding. It’s a problem that’s already being felt at the consumer level, with some PC builders already reporting price rises of around 95%.
Where the analogy gets interesting
The Pokémon market has seen similar efforts in recent years, like the significant scalping of the 151 set, which featured the original 151 Pokémon. Scalpers here sought to bank on the demand for that nostalgia to such an extent that it created an immediate scarcity.
But unlike the memory market, collectors are starting to call the scalper’s bluff, and instead of paying artificially inflated prices, are instead choosing to simply wait patiently.
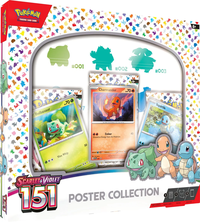
The result? Within days of release, scalpers began slashing prices simply because they hadn't sold their stock straight away.
The question hanging over the AI chip market is whether the same correction is possible, or whether the stakes are too high and the players too capitalized to blink. Venture funds sitting on GPU allocations aren't hobbyists who need to clear inventory before rent is due. OpenAI isn't a reseller who overestimated demand for a booster box.
Then again, neither were the crypto miners who stockpiled GPUs in 2022, only to watch prices collapse when Ethereum moved to proof-of-stake.
The vast majority of the chips being snapped up in the GPU realm are amortized over several years for huge sums of money. And if recent reports about OpenAI’s potentially dubious finances are to be believed, it could only be a matter of time before things level out.
The semiconductor space has routinely seen peaks and troughs, rises and busts, more than most other modern industries. The chip industry in the 1990s alone was marked by dramatic economic fluctuations, with an explosion at a Japanese cresol factory causing supply shortages midway through the decade, followed a few years later by a period of intense demand, which preceded the eventual bursting of the Dot Com Bubble.
What the semiconductor space can learn from Pokémon that it can’t from other bubbles – be they Beanie Babies or digital pictures of apes – is that artificial scarcity only works until buyers decide it doesn't. Silicon speculators would do well to remember: even the rarest card is worthless if no one's willing to play.


Comments