

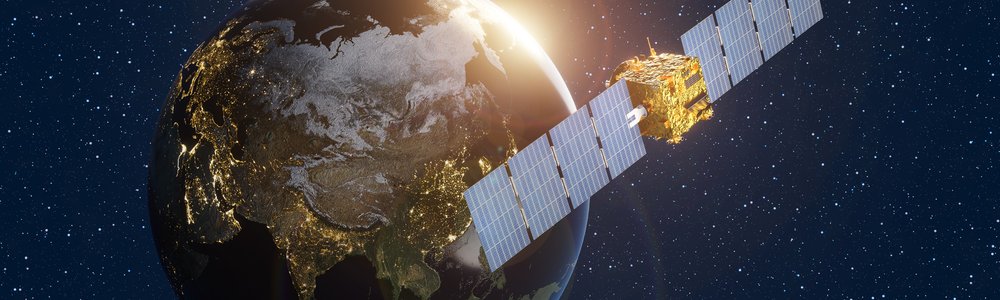
Mavenir – the beleaguered cloud-native network infrastructure provider and one-time open radio access network (RAN) zealot – scored a notable deal to provide satellite communication operator Iridium with a core network platform to support the operator’s direct-to-device (D2D) service.
The deal calls for Mavenir to supply its containerized Converged Packet Core product riding in Amazon Web Services’ (AWS) multiregion cloud infrastructure to Iridium. The Mavenir platform provides a handful of core network functions, including converged session management function, converged user plane function, policy control, subscriber management, network exposure function, and messaging capabilities.
The Mavenir platform will integrate into Iridium’s existing provisioning and billing systems, with support for narrowband-IoT (NB-IoT) traffic delivery across multiple interfaces. This includes IP, UDP, TCP, and non-IP data delivery.
Iridium is also claiming future plans to support 5G New Radio (NR) that will allow the operator to use the same backend infrastructure as it migrates to D2D services.
Mavenir’s market shift
Surprisingly, the Iridium deal does not mention anything about AI, which Mavenir management touted as one of the vendor’s big focus areas following its financial restructuring earlier this year. That restructuring had long-time investor Siris recapitalizing Mavenir to the tune of $300 million in new investments and, more importantly, Mavenir eliminating more than $1.3 billion in existing debt.
Mavenir at that time said it planned to use the new funds to “double down on its profitable Core segment,” which includes software tied to voice, messaging, video, and data services. It will then be “refining its open RAN investments to prioritize software in 4G and 5G deployments,” and “maintain” its current open RAN hardware IP to continue supporting its existing customer base.
The vendor also noted that it would use the new capital to boost AI capabilities in its systems. This includes the greater ability for controlling network assets and driving new revenue streams from those deployments.
“Now we are on to a new journey of creating true AI-native telco stack,” Mavenir CEO Pardeep Kohli noted in a LinkedIn post tied to the new funding and focus. “My [belief] is that with AI, traditional mobile network operators will see significant changes.”
That AI focus aligns with the growing move to include AI in RAN deployments. Analysts have pointed to the benefits AI can bring to the deployment and management of cloud-based open RAN networks, which are more complex orchestration challenges due to the disaggregated multivendor ecosystem. The use of AI could help close performance gaps for open RAN architectures compared with legacy RAN models.
That new focus is increasingly significant for Mavenir as its legacy open RAN operations continue to struggle.
Mavenir’s open RAN business counts a number of established operators like AT&T and Virgin Media O2. However, it also had a significant presence in Boost Mobile’s unique open RAN-based 5G network deployment, which is now in the process of being decommissioned.
Satellite competition
That Boost Mobile decommissioning by its parent company EchoStar tangentially also puts more pressure on Iridium.
Just weeks after EchoStar signed a deal to sell spectrum assets to AT&T and recoup a mobile virtual network operator (MVNO) agreement as part of that return to host Boost Mobile, EchoStar also sold a significant chunk of spectrum to satellite communication giant SpaceX.
SpaceX’s Starlink service is viewed as the satellite communication space’s most robust competitor. The provider has more than 600 satellites in low-Earth orbit (LEO) to support its D2D service, which counts dozens of mobile operators as customers, and more than 8,000 satellites in orbit for its broadband offering.
Iridium has been working toward taking a piece of this market opportunity. The company early last year unveiled its boldly named “Project Stardust,” which was based on the company’s existing LEO satellite constellation to support standards-based 5G services.
Iridium is working toward commercial launch of its D2D service next year, and recently signed a deal with German telecom giant Deutsche Telekom to support IoT-based tracking services.
ABI Research has predicted the direct-to-cellular market will generate $11.6 billion in revenues by 2030, with the IoT space itself generating $4 billion in revenues. More broadly, the analyst firm sees nearly $125 billion in revenue opportunities for the space by 2030, citing market opportunities like IoT, backhaul, commercial broadband, and mobile satellite services.
“We are seeing that the market is evolving quickly, and many services are finding enhanced deployment through strategic alliances and from increased bandwidth supply in LEO,” Jake Saunders, VP of Asia Pacific at ABI Research, wrote. “With satellites becoming smaller, more affordable, and reaching closer orbits, the barriers to entry have been lowered, fostering innovation and expanding the scope of satellite-based services and applications. The market is revealing new development paths that will influence the terrestrial and non-terrestrial connectivity markets and shape enterprise opportunities throughout the telecommunications value chain.”
However, analysts have also started to question the ability for the market to support several satellite-based service options, especially if they try to compete on a level-playing field with already established terrestrial-based telecommunication providers.
Analysys Mason in a report last year wrote that the satellite communication industry is quickly moving from a legacy of limited capacity to one of abundance, which will produce new challenges.
“For an industry that has been defined by niche markets and scarcity economics, the shift to abundance is a new paradigm; with its own challenges and opportunities,” Analysys Mason’s Christopher Baugh wrote. “A broadening industry scope could fuel revenue growth for years, which could benefit several satellite players. In addition, some players may be required to make risky strategy decisions and not all will succeed.”
Those strategy decisions will need to straddle a thin operational and partner line.
“Looking at these market opportunities, a thought may arise whether satellite operators are trying to disrupt the traditional telecom market. But the reality is that telcos will continue to be the primary service provider for wireless access,” MTN Consulting’s Arun Menon wrote in a report. “Telcos are also going to benefit from partnerships with satellite operators as they will aid in providing an enhanced experience for telco customers, reinforced by ubiquitous coverage. For satellite operators, though, navigating the regulatory hurdles and ensuring constant capital flow are key concerns; several players from the current herd will vanish in the next three to five years.”
More in The Cloud & Storage Channel
-
-
-
Episode Is data AI’s biggest bottleneck?
Comments