

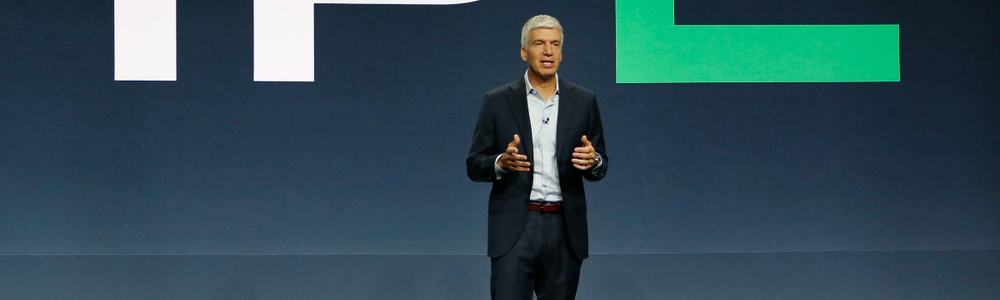
SUNNYVALE, California – Hewlett Packard Enterprise (HPE) Networking head Rami Rahim triumphantly raised integration “cost synergies” tied to the vendor’s $14 billion acquisition of Juniper Networks and bolstered segment-related forecasts over the next several operating years, moves linked to surging AI-related expectations and what the former Juniper CEO said was a continued smooth integration progress.
Rahim made the proclamation on stage during the vendor’s networking investor day, laying out that Juniper Networks-related cost synergies would hit an $800 million run rate by the end of its fiscal 2028, which is currently scheduled to be the end of October that year. That figure compared with HPE CEO Antonio Neri’s initial claim of between $450 million and $600 million in savings within three years of the deal closing, which would be mid-calendar year 2028, or two-thirds of the way through the third quarter of HPE’s fiscal 2028.
HPE also increased full-year networking segment revenue growth forecasts from as high as 17% that company management outlined during the most recent third-quarter (Q3) earnings call to now as high as the “low-20s percent,” though it maintained its mid-to-high 20s percentage range forecasts on networking segment margins.
Rahim also noted an increase in projections for networking segment revenue to grow at a high-teens percent compound annual growth rate (CAGR) from its fiscal year 2026 through fiscal year 2029, and also expectation that the segment will maintain an operating margin target of mid-to-high 20s percent from fiscal year 2027 through fiscal year 2029.
Rahim also noted that HPE had doubled its networking purchasing commitments sequentially, a move that further bolstered the vendor’s robust outlook. This followed comments from HPE CEO Antonio Neri during the vendor’s most recent earnings call that supply chain hurdles had limited the vendor’s networking sales growth.
Operational tailwinds
Rahim told SDxCentral in a one-on-one interview at the event that this robust forecast was based on a pair of market conditions.
“The market itself has accelerated, there's no doubt about it. I mean, the pace of investments that are happening in data center infrastructure have outstripped our expectations. There's significant market tailwinds across all of our different market categories,” Rahim said. “But then the second thing that has happened from a year ago is that the proof points of our ability to execute through this integration are definitely there. And so it's a combination of more tailwinds from the market across all of our strategic segments coupled with more confidence in our execution that comes from a year's worth of actually working through some of the biggest challenges that typically come with integration, has given us the confidence to essentially up our guidance for this year as well as for the next three years.”
That tailwind was highlighted by a pair of recent contract wins. This included HPE scoring a “gigawatt scale” networking deal with Oracle and its more recent $1.2 billion deal with neocloud Vultr.
Rahim said those deals show how HPE’s portfolio breadth is helping its networking business.
Rahim told the investor conference audience that the Helios platform opens deal “an entirely new addressable market in networking, either by selling our AMD Helios networking trays as part of an HPE integrated rack solution or independently to other solution providers. We believe Helios represents more than a billion-dollar networking opportunity over the next two years, with networking tray orders having already exceeded $200 million.”
Rahim’s financial confidence came just a month after HPE posted robust third-quarter earnings, bolstered by strong networking segment results. This included a 75% year-over-year increase in segment revenues to $2.9 billion – though a more modest 10% increase on a normalized basis.
HPE CFO Marie Myers during that earnings call did note networking-related orders increased 36%, which was 3.5-times faster than revenues, with its data center networking, routing, and security operations all posting outsized segment growth.
Can HPE target Cisco, Arista?
Analysts noted the increased forecasts could position HPE to drive more investment or pricing opportunities into its networking division compared to rivals.
“From our perspective, by expanding its annual cost-synergy target to $800 million by FY28 [fiscal year 2028] following the Juniper acquisition, HPE secures a structural margin advantage over Arista and Cisco that can be reinvested into [research and development] and competitive pricing,” Ron Westfall, VP and practice leader for infrastructure and networking at HyperFrame Research, wrote in a research report tied to the event. “These operational savings directly fund an upgraded FY27–FY29 revenue [compound annual growth rate] in the high-teens with mid-to-high 20s operating margins, giving HPE the financial latitude to challenge incumbent market shares across campus, routing, and data center fabrics.”
HPE has moved to be more aggressive in the market, including its move earlier this year to double its pricing quote validity from 15 days to 30 days. That announcement came as part of HPE’s Partner Growth Summit and garnered a resounding round of applause from the thousands of event attendees.

Comments