

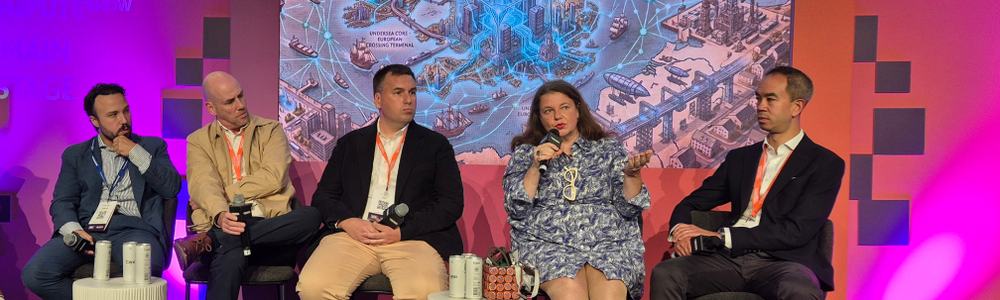
LONDON – Europe may not be able to match the giant AI data centers rising across the U.S., but panelists at this week’s Xcelerated Compute event argued that chasing raw gigawatts could be the wrong race anyway.
The more realistic opportunity may lie in smaller inference facilities closer to users, infrastructure for Europe’s software innovators, and getting viable capacity online before today’s assumptions become obsolete.
That does not mean the market will be small. Brian Burns, partner at PwC, predicted that $31.6 trillion will be spent across data centers, chips, and replacement cycles between now and 2050, including more than $1 trillion this year.
“This is the first time in my career that I’ve been talking about markets in trillions of dollars,” Burns said. “If I think about a million seconds ago, I think that was last Friday. If I think about a trillion seconds ago, that was the last ice age.”
Rather than demand or capital, he argued, the constraint will be the industry’s ability to deliver, including its supply chains, equipment, people, and processes.
Welcome to the ‘bragawatt’ era
That distinction matters because project announcements and infrastructure that will actually be built are two different things.
“We went from megawatts to gigawatts to 'bragawatts,'” Burns said. “It’s very easy to write a press release and say we’re going to build X.”
Before treating a project as real, PwC looks for an identified site, grid and network connectivity, an off-taker, and a credible route to commercialization.
Rob Reid, director of hyperscale and strategic accounts at Zayo Europe, encounters proposed projects at an even earlier stage, when developers request rough estimates for connecting prospective sites.
“We’d often offer a lot of finger-in-the-air, tire-kicker estimates, saying it’ll cost £10 million or £15 million to build it in a field outside Glasgow,” Reid said. “I would say 5% of those proceed, and 95% never go anywhere.”
Speculative applications can make promising markets appear more crowded than they are. Giorgio Sbriglia, CEO and chairman of Norwegian AI data center provider Terakraft AI, said land with a Nordic power reservation can command around $573,000 per megawatt, creating an incentive to secure capacity whether or not a viable project follows.
Norway has responded by requiring applicants to provide financing and business plans and meet project milestones or risk losing their allocation.
“Most of the game is hoping that a competitor doesn’t meet a milestone so you can get the power,” Sbriglia said.
As Sebastian Moss, executive editor at DatacenterDynamics and moderator of the panel, observed, building a business plan around somebody else’s business plan going awry does not exactly make for a comfortable foundation.
Go where the capacity is real
The Nordic countries gained an early advantage from abundant power and a cooler climate, but suitable sites are becoming harder to find. Reid said Zayo is also seeing activity in Iberia and France, where lead times for large grid connections can be shorter.
For Sbriglia, this changes the calculation for developers.
“Where AI infrastructure gets built is where you can go fast,” he said. “It’s not enough to have the power. It’s not enough to have the reservation.”
That could give comparatively expensive markets, including the U.K., an opening if they can bring capacity online quickly enough to meet immediate inference demand.
Europe must nevertheless be realistic about the scale it can support. Chris Yiu, director of public policy for Northern Europe at Meta, pointed to the company’s Hyperion development in Louisiana, which is targeting around one gigawatt initially and could grow much larger.
“If you were to superimpose that data center on central London, the footprint would go from here, where we’re sitting, to the O2 in North Greenwich,” Yiu said.
Reid said the gulf between the raw gigawatts being built in the U.S. and what Europe can deliver over the next five years is too great for the region to compete seriously in frontier-scale training infrastructure.
Smaller may be smarter
“I don’t think we are going to need nearly as many of these giant data centers as we think,” OpenUK CEO Amanda Brock said.
Frontier model development is dominated by companies with deep pockets, she said, but smaller businesses are adapting existing models, while other innovators build infrastructure, agents, and agentic frameworks around them.
Brock expects more processing to move onto personal devices, alongside greater demand for smaller edge facilities that can reuse existing buildings. Reid similarly identified inference at the edge as Europe’s most promising opportunity, with smaller pools of graphic processing units (GPUs) distributed closer to users, regulators, and demand.
Efficiency could also change the calculation before Europe completes a generation of giant infrastructure projects.
“In the longer term, I think we need to capitalize on innovation and solve problems for the future, not for the present,” Sbriglia said.
Europe would often need to build both a data center and the power generation supporting it, he noted. By the time that infrastructure becomes operational, more efficient chips and computing architectures may have changed the requirements it was designed to meet.
Asked where they would build in Europe today, Reid and Sbriglia both settled on France, with Sbriglia citing its combination of policy, infrastructure, and talent. Brock, meanwhile, held out hope for the U.K.’s technical talent and innovation.
The answer may be less satisfying than a neat pin on a map. Europe’s next AI infrastructure will be built wherever developers can combine real power, connectivity, customers, and political will quickly enough to beat both their competitors and the next change in technology.


Comments