


Ciena entered 2026 riding high on an AI-powered wave, momentum it expects to continue to surf despite potential competitive changes from rivals like Nokia, Cisco, Broadcom, and Marvell.
David Rothenstein, SVP and chief strategy officer (CSO) at Ciena, told an audience at this week’s Needham Growth Conference that competitors in the broader WAN-based optical systems business “has thinned considerably for those of us that have been doing this a long time,” but rivals still remained.
Rothenstein somewhat quickly ran over Huawei as a direct rival, though he did note that the China-based vendor “still exists and still does very well,” before pointing more specifically at the recently Infinera-bolstered Nokia.
“We're really looking at us and Nokia with the combination of Infinera, and what I would say about that combination is we competed very effectively against both when they were standalone companies, and we continue to compete effectively with them now as a combined company,” Rothenstein claimed.
However, despite that regard, Rothenstein did point to integration challenges still ahead for its rival.
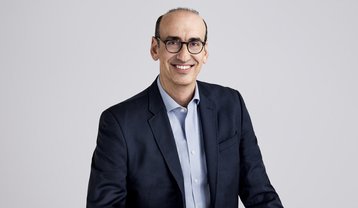
“They have some work to do, I think, in terms of integration and portfolio rationalization, but they're a big, well-resourced competitor who we don't take lightly,” Rothenstein added.
Nokia for its part has been throwing around those resources.
The vendor recently laid out plans to invest up to $4 billion to build out its research and development (R&D) and manufacturing capabilities in the U.S. That proposed multi-year investment will see some $3.5 billion go toward R&D efforts across mobile, optical, and data center networking technologies, with $500 million invested in manufacturing at sites including Texas, New Jersey, and Pennsylvania.
Nokia CEO Justin Hotard said the investment will “strengthen the [U.S.]’s capacity to deliver greater security, productivity, and prosperity through AI-optimized connectivity at scale, while advancing the newest research and innovation that will shape the future of networking for the years to come.”
Rothenstein’s Nokia focus is warranted. Dell’Oro Group recently reported that Ciena and Nokia both posted a notable increase in market share through the first nine months of 2025.
Cisco ‘doing quite well’
Rothenstein also noted that Cisco has “been doing quite well” integrating its Acacia assets, including the vendor’s “really deep focus and deprioritizing optical systems writ large for quite some time. So we see them more in terms of the pluggable” market “more than anything else.”
Cisco has touted that Acacia-based success, reporting strong demand during its most recent fiscal quarter for its coherent pluggable optic offerings, with CEO Chuck Robbins noting that “all hyperscalers are now customers of these products.” This has provided Cisco with participation both inside and outside of the data center.
“We're blessed to have great solutions in both inside the data center and then outside the data center, DCi (data center infrastructure) scale across,” Robbins said during Cisco’s most recent earnings call. “I think we'll continue to innovate there. … We now are selling our pluggable optics to all of the hyperscalers, all the major hyperscalers, and I think that we'll continue to see great opportunities across both of those. … It's a really large market that is meaningful, even on par with sort of the switching side of it, so we're pleased to be [on] both sides of it.”
Ciena has also touted its customer base, though most of its revenues come from a smaller pool. During its most recent earnings call, Ciena’s management noted that three customers represented 43.6% of Q4 revenue: two unspecified customers, along with AT&T, a dramatic dependency for a company with more than 1,700 customers worldwide. For the entire fiscal year, just two customers accounted for 28.4% of total revenue.
While the vendor failed to specify who those customers were, CFO Mark Graff revealed one was a cloud provider, the other a service provider.
Ciena’s efforts have seen a rise in customers outside its traditional telecom base. The vendor reported that 55% of Q4 revenue came from non-telco customers, with direct cloud providers growing 49% year-over-year to represent 42% of total revenue.
Will Ciena acquire?
Outside of noted rivals Nokia and Cisco, Rothenstein acknowledged large players like Broadcom and Marvell were competitors in the “shorter distance applications,” though that was a different competitive dynamic.
“In some cases who we compete with, in some cases a bit complementary, and that competitive landscape will continue to evolve over time,” Rothenstein explained.
That evolution could also be impacted by Ciena’s own internal decisions.
Rothenstein described his “philosophy” on mergers and acquisitions (M&A) as being a “serial acquirer” within reason.
“We're not going to be doing 20 deals a year, but we have done a lot, and we'll continue to do more deals,” Rothenstein said. This includes Ciena’s $270 million deal last year to acquire optical technology company Nubis Communications.
Rothenstein furthered that philosophy by noting M&A was but one leg of Ciena’s capital management alongside organic research and development and the return of capital.
“I think we have been very thoughtful deployers of capital on an organic basis, but why we do M&A [is] to bolster our position in the core business, to accelerate our position in an adjacent business, fill in gaps from a technology or go-to-market standpoint, drive cost and revenue synergies, or ideally, some combination of all of the above,” Rothenstein said. “That was behind the Nubis acquisition, behind a lot of the ones we've done in the past.”
That philosophical success can be seen in Ciena’s most recent earnings. The vendor ended its fiscal 2025 showing robust year-over-year momentum, including a 19% increase in full-year revenues, and expects that growth to accelerate to 27% for fiscal 2026.
“I think it's hard not to be accused of exaggeration when we talk about industry dynamics and the kind of demand that we're talking about across the portfolio, across these market and technology applications and use cases … and I'm not blaming anyone. I’m still getting my head around it. We’re still getting our heads around it as a business,” Rothenstein concluded. “I think the market is still maybe not fully appreciating the speed and the scale of these dynamics, which, for those who has been doing this for a long time, are wholly unprecedented to anything we've seen in the past three decades.”

Comments